What Is a Pension Sharing Order? A Guide to Splitting Pensions in Divorce
After the family home, pensions are often the largest asset a couple owns. They are also the ones most easily overlooked when finances are divided in a divorce. Pensions built up during a marriage are usually treated as shared assets in England and Wales, even if they are held in one person's name.
This guide explains what a pension sharing order is, how pensions are valued and the alternatives to sharing. It also covers how an order is made and the mistakes that can leave one person worse off in retirement. If you are working out how money, property and pensions will be divided, it gives you a clear starting point.
How a Pension Sharing Order Works
A pension sharing order is a court order that transfers a percentage of one person's pension into a pension in the other person's name. The person giving up part of their pension is left with what's called a "pension debit". The receiving spouse gets a "pension credit" of the same value. Depending on the scheme, that credit either remains within the same scheme as a new pension or is transferred to a pension of the receiving spouse's choice. Once it is done, each of you owns your own pension outright, which gives you a clean break from each other's retirement savings.
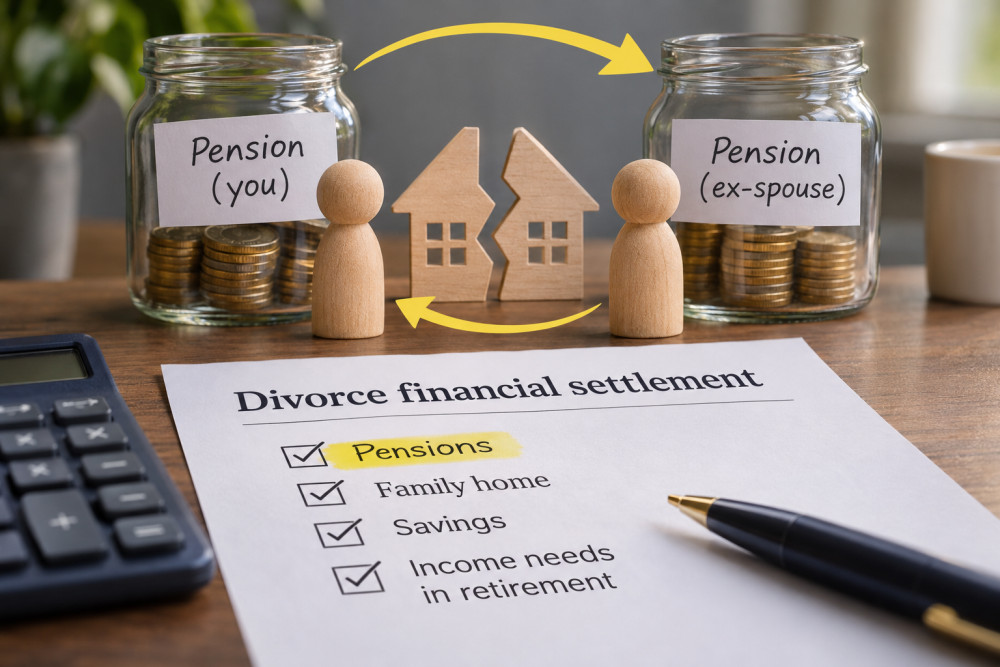
Pensions are not usually considered in isolation. Any split will be weighed against the family home, savings and each person's income needs in retirement, so the right percentage depends on the whole picture. If you would like advice on how pension sharing in divorce fits with the rest of your settlement, Stowe Family Law, ranked as a leading firm across the UK by the independent legal directories Chambers & Partners and the Legal 500, can help you work through the options. It is worth gathering your latest pension statements before any first meeting. These show which schemes you hold and give your solicitor a starting point for the valuations described below.
Finding Out What Your Pensions Are Worth
Every pension needs a valuation before a fair split can be agreed. The standard figure is the Cash Equivalent Transfer Value (CETV), which is the amount the scheme would pay if the pension were transferred elsewhere. You will need a CETV for each pension you hold, as both of you must include these figures on Form E, the financial statement used in divorce proceedings. Here is how to get them:
- Contact each pension provider and ask for a CETV for divorce purposes.
- Allow up to three months, as that's how long providers can take.
- Check if there is a charge, as most schemes give one free valuation every 12 months.
A CETV divorce figure can be misleading for some pensions, especially defined benefit (final salary) schemes and public sector pensions, such as those for teachers, NHS staff, police or armed forces. Their CETV may not reflect the income they will pay in retirement. A Pension on Divorce Expert (PODE), a specialist actuary, can produce a report comparing pensions on a fairer basis. Ask your solicitor if one is needed in your case.
Choosing Between Pension Sharing, Offsetting and Attachment Orders
Pension sharing is not the only option. There are three main ways to deal with pensions on divorce:
- Pension sharing: a percentage of the pension is transferred to the other spouse, giving each of you your own pension and a clean break.
- Offsetting: one person keeps their pension, and the other receives a larger share of another asset, such as the home or savings. This can suit someone who wants to stay in the property, but pensions and cash are not worth the same pound for pound because of tax and access rules.
- Pension attachment orders: part of the pension income or lump sum is paid to the ex-spouse once the pension starts paying out. Payments usually stop if the receiving spouse remarries, and the person who owns the pension controls when it is drawn.
Think about your own priorities when comparing these. Is staying in the family home more pressing than retirement income? Do you need complete independence from your former partner? Your solicitor and a financial adviser can model each option so you can see how they would affect you both in the short and long term.
Getting a Pension Sharing Order Approved by the Court
A pension can only be shared through a court order, even if you and your spouse agree on everything. Once you have agreed the percentage, your solicitor drafts a consent order setting out the full financial settlement. They attach a Pension Sharing Annex (Form P1) for each pension being shared. The court can only approve the order after the conditional order in your divorce has been made, and the share takes effect after the final order.
A pension sharing order UK schemes receive must include the exact percentage and the scheme details, so accuracy matters at the drafting stage. After the order takes effect, the provider has four months to carry out the transfer, starting from when it has all the paperwork it needs. Providers can charge fees for this. Agree in advance who will pay them, and record it in the order.
Avoiding Common Mistakes When Splitting Pensions
Small oversights can have a lasting effect on retirement income. Watch out for these pitfalls:
- Applying for the final order too early. Ending the marriage before your financial order is approved can mean losing rights to a spouse's pension if they die first.
- Relying on CETV figures alone. Two pensions with the same CETV can pay very different incomes.
- Forgetting about the State Pension. The new State Pension generally cannot be shared, though some older entitlements can.
- Overlooking tax and fees. Pension income is taxed, and both providers may charge for implementing the order.
- Leaving pensions out altogether. Without a court order, either of you could make a pension claim in future.
Check each of these with your solicitor before signing anything, and keep copies of every valuation and letter from your providers.
Get Advice Before Agreeing How to Split Pensions
Splitting pensions fairly means getting accurate valuations, comparing the options against your other assets and making sure any agreement is turned into a court order. Taking your time over these steps can protect your income for decades to come.
Before you agree a percentage or trade a pension for a bigger share of the home, speak to a family solicitor about your circumstances. Where your pensions are large or hard to value, advice from a financial adviser or pension expert can give you more confidence that the settlement will work for you in retirement.
New alsager Jobs Section Launched!!
Vacancies updated hourly!!
Click here: alsager jobs
Share: